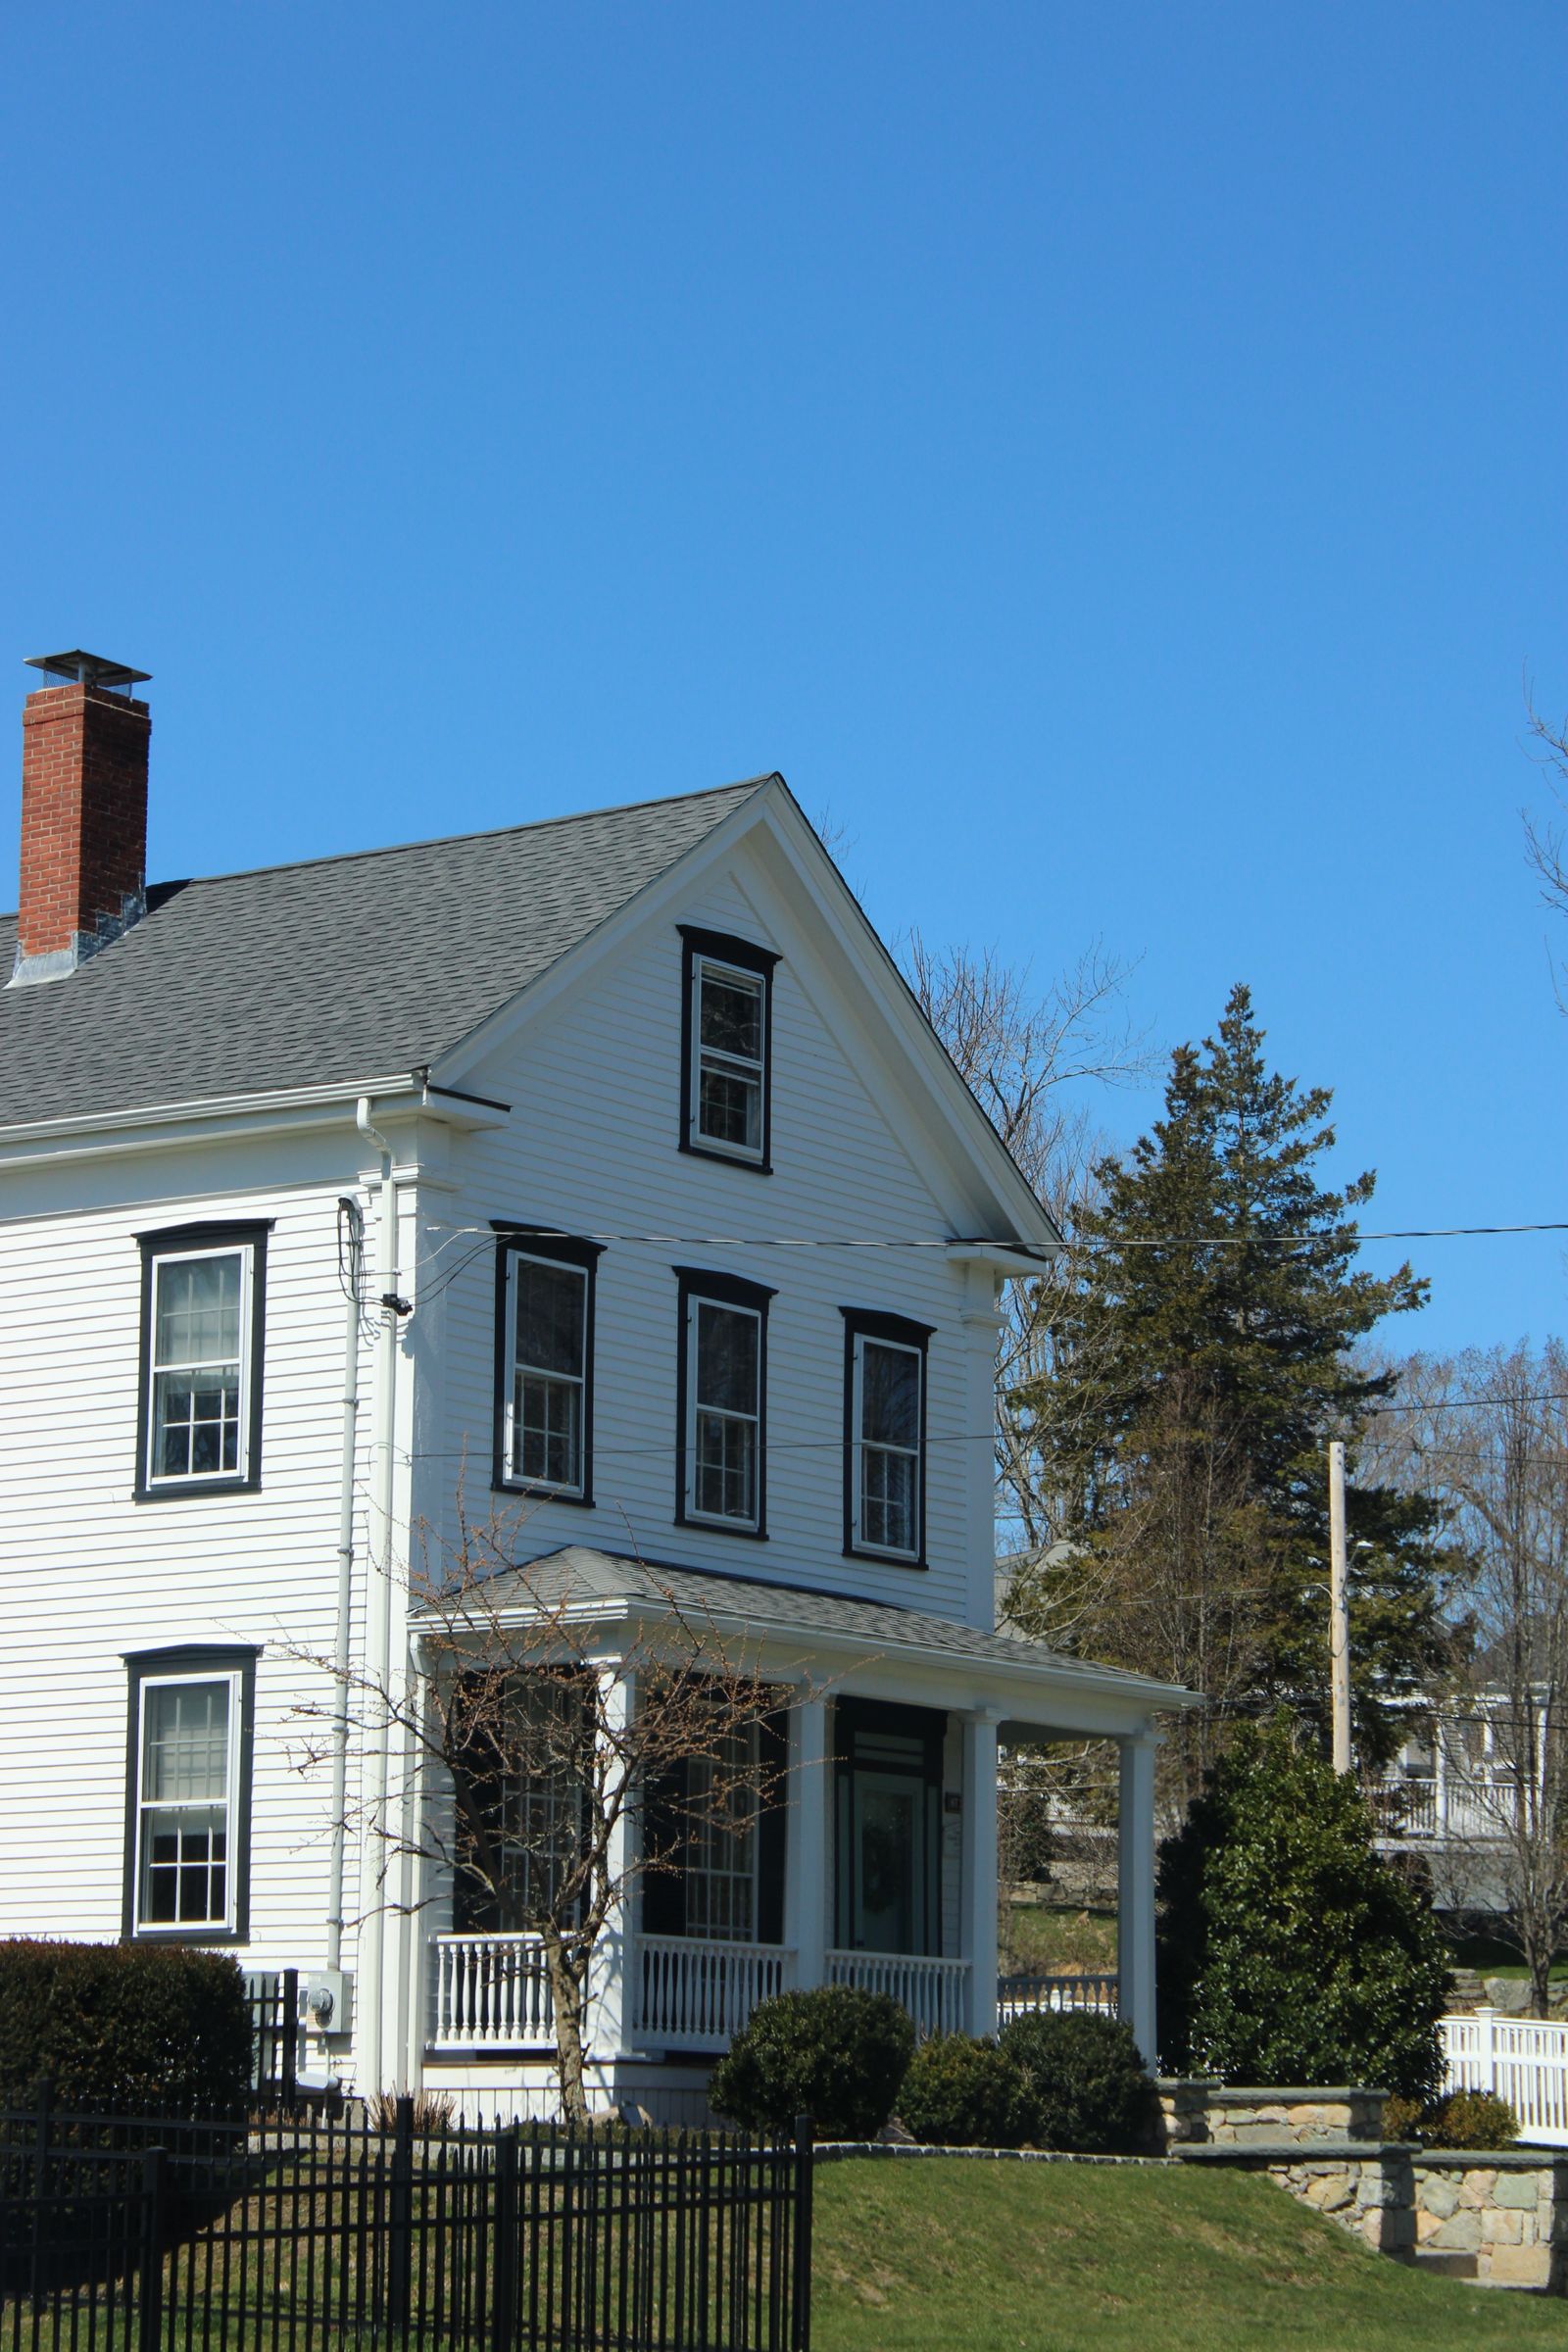
Homes on the market10 active Triangle listings, updated this week
- $689,000New listing
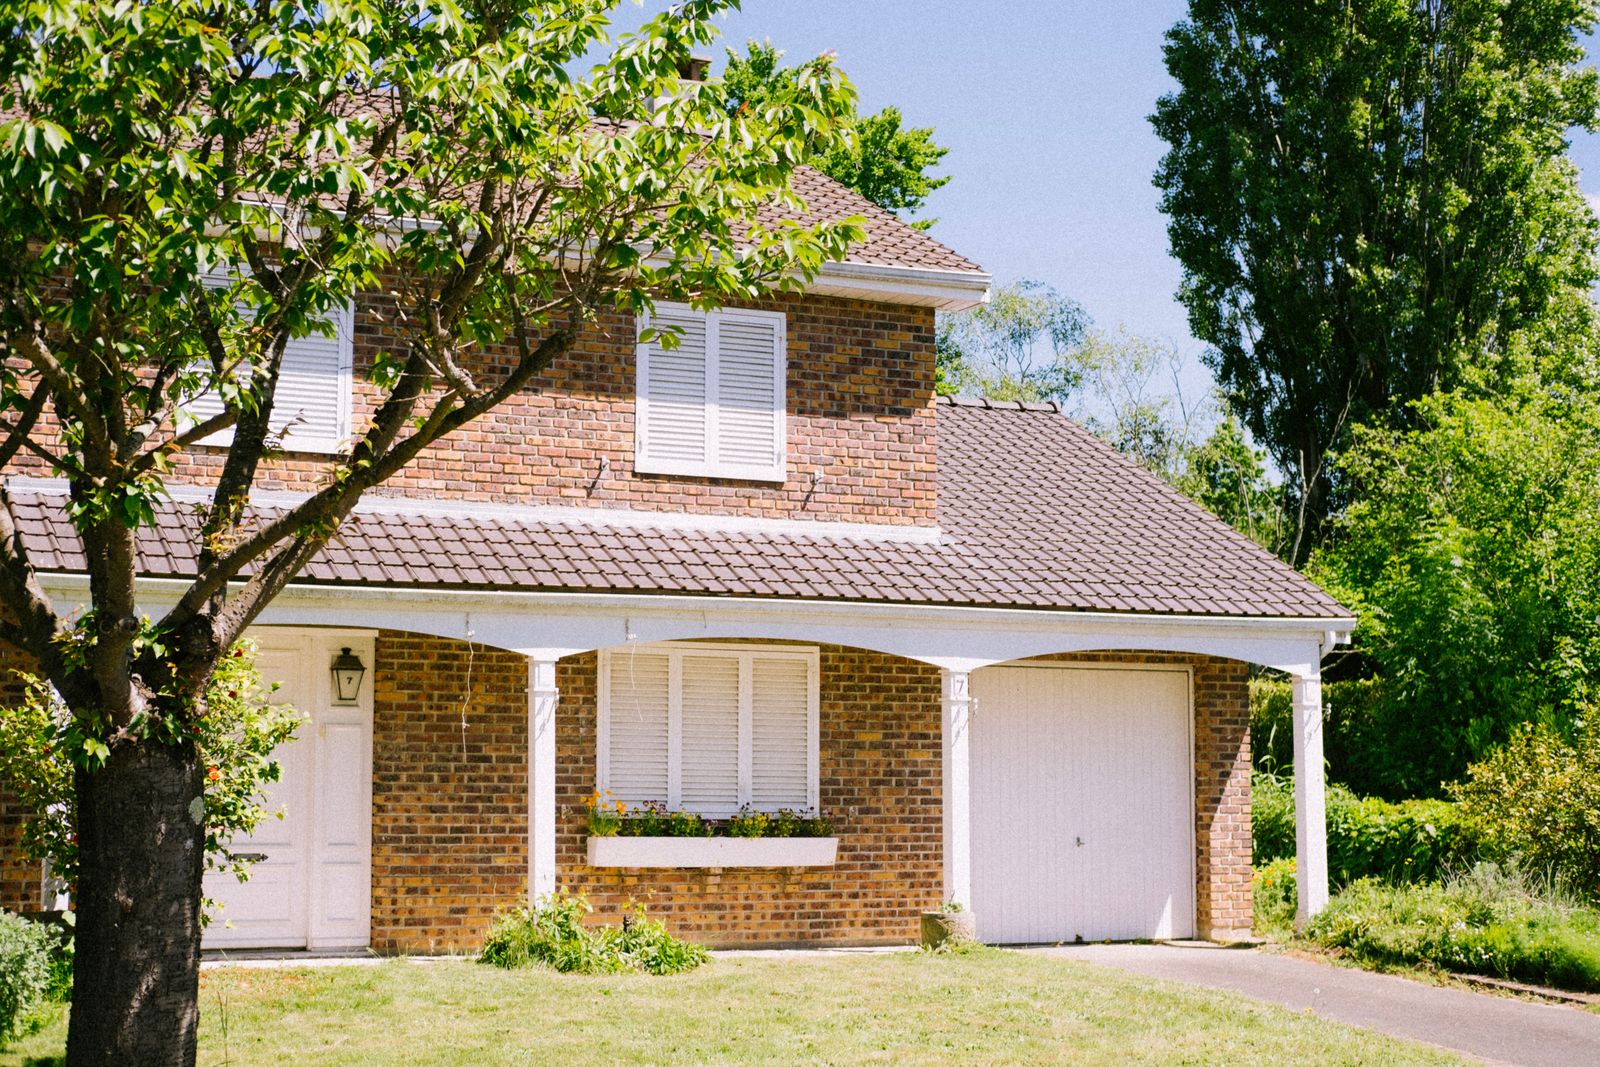
- $749,000Open Sat 1 to 3
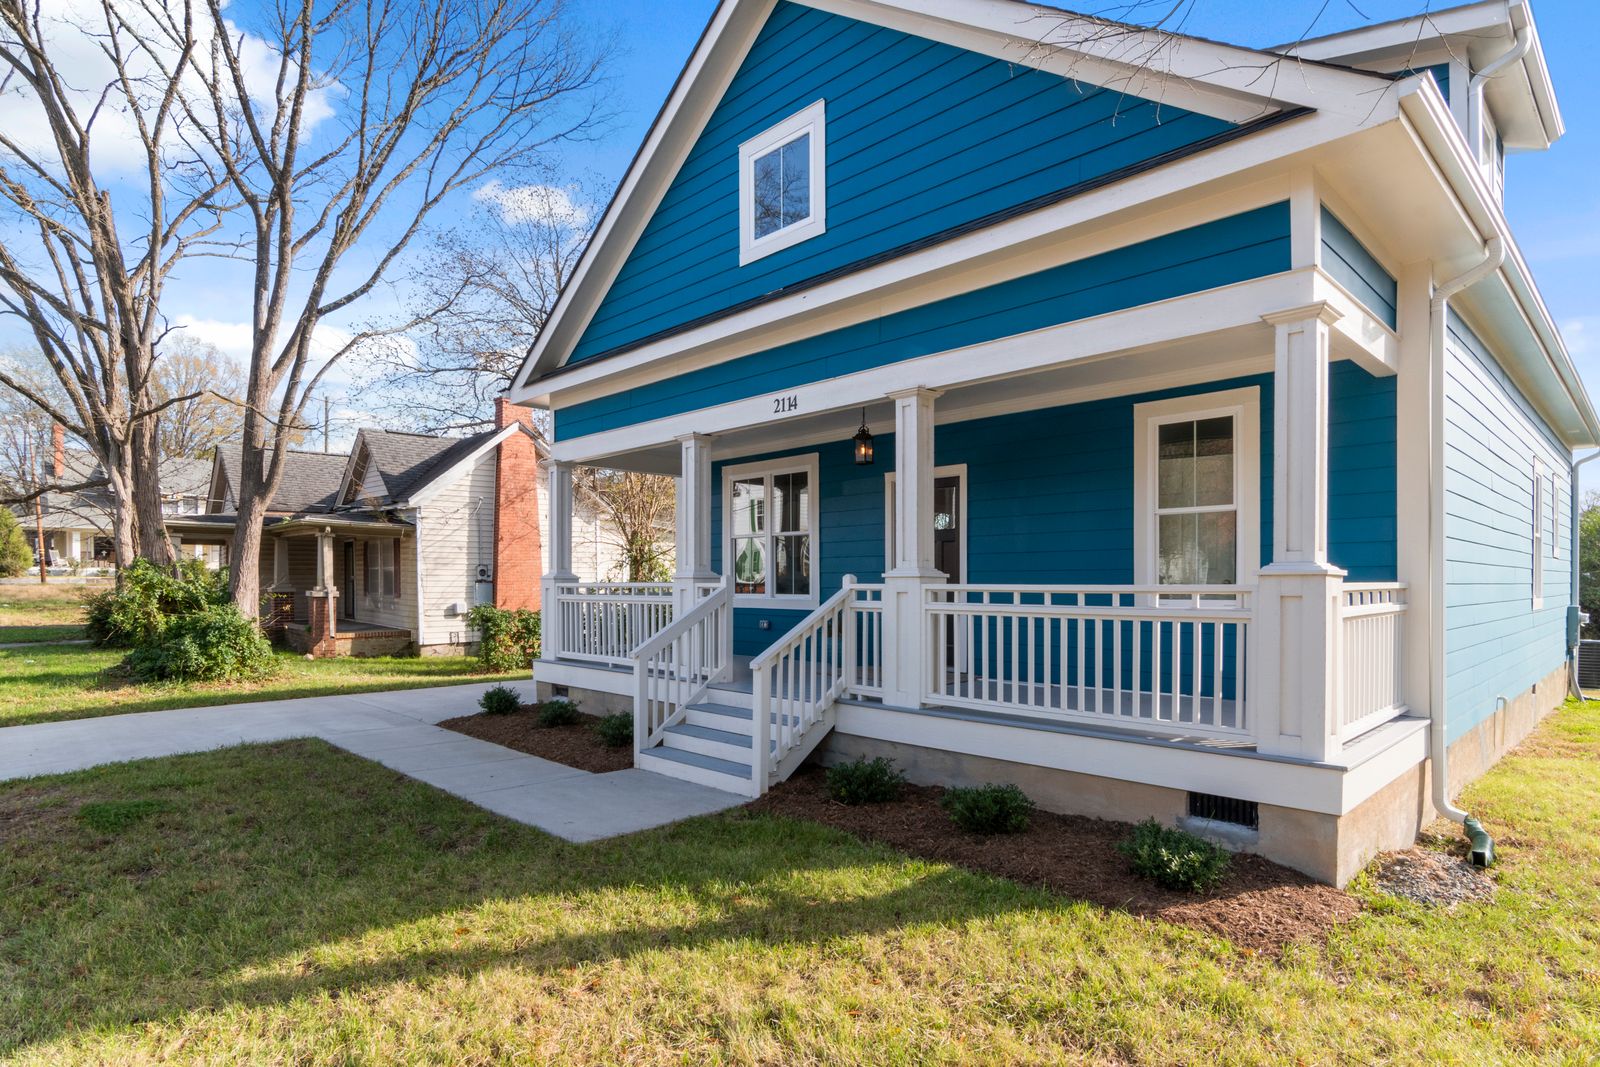
- $715,000Price improved
Live preview
Pick a color combo or choose your own. The whole website updates as you go, on every page.
Showing the original colors.
Buy this design, or get one built like it with your info, branding, colors and locations.
Buy this website100+ website designs at Prebuiltwebmarket.com
Raleigh, Cary, Wake Forest and Apex
Homes for sale, area figures, and the five pieces of paperwork that decide whether a deal holds together. Start anywhere.
Our 2025 listings sold at 101.6% of list price in a median of 19 days (sample figures). The three-week launch plan is written out in full.
Before we show you a single house, North Carolina requires a written buyer agency agreement with a compensation figure in it. Here is where that figure comes from, in the order we try.
Listing firm offers compensation off-MLS
We confirm the offer in writing before you tour, because it can no longer be published in the MLS.
Seller concession in the offer
A concession is money the seller nets less of, so it is weighed against your price the same way a repair credit is.
Buyer pays the balance at closing
Not financeable on a conventional loan. We model it into your cash to close before you sign anything.
Whichever route applies, the number is written into your agreement before the first showing and restated in writing before every offer. Nobody should learn what their agent is paid from a settlement statement.
Sample medians and ratings. Verify school assignment with WCPSS.
North Carolina's Offer to Purchase and Contract splits your money in two. Most buyers coming from another state get this backwards, which is expensive.
Due diligence fee
$500 to $2,500 (sample)
It buys you the right to walk away for any reason at all until the deadline. In a bidding war it is the number sellers look at after price.
Earnest money deposit
About 1% of price (sample)
Terminate before 5:00 p.m. on the due diligence date and it comes back. One minute after, it goes to the seller.
Both at closing
Full amount
Neither is an extra cost if you close. They are the price of the right to change your mind.
Contract signed, fee delivered
Due diligence fee to the seller, earnest money to the closing attorney's trust account, and the executed contract to your lender the same afternoon.
Inspections booked
General inspection, plus radon where the geology calls for it, sewer scope on anything pre-1985, termite (wood-destroying insect report) and a structural engineer if the general inspector flags movement.
Loan application and appraisal ordered
The lender cannot order the appraisal until you formally apply. In Wake County a residential appraisal typically comes back in 7 to 12 days (sample).
Reports in, repair request drafted
We separate safety and structure from cosmetics, then ask for repairs, a credit or a price reduction. The seller is not obliged to agree to any of it.
HOA documents and survey
Statement of unpaid assessments, declaration, budget and minutes requested. A boundary survey is ordered here if fences, driveways or additions look close to a line.
Appraisal returns, insurance bound
If value comes in under contract price, the appraisal gap conversation starts now, while you still have a free exit. Homeowner's insurance quote and flood determination in the same week.
Repairs agreed or terminate
Anything unresolved has to be settled before the deadline. Extensions are possible but require the seller's written agreement, usually for an additional fee.
Due diligence ends
From this moment your earnest money is at risk. The remaining work, clear-to-close, final walk-through and attorney settlement, runs to the settlement date.
| Document | What it tells you | What we flag |
|---|---|---|
| Statement of unpaid assessments | Dues owed on this unit through closing | Any balance the seller has not budgeted to clear at settlement |
| Declaration and covenants | What you may build, park, rent or paint | Architectural approval required for work the seller already did without it |
| Bylaws and rules | How the board is elected and what it may fine | Fines that run with the property rather than the owner |
| Current budget and balance sheet | Dues in, expenses out, reserves held | Reserves under about 30% of the reserve study recommendation |
| Reserve study | Roof, siding, paving and pool replacement schedule | A roof at year 22 of a 25 year life with no line item funding it |
| Two years of board minutes | What the board has been arguing about | Repeated discussion of a special assessment that has not been voted yet |
| Insurance certificate | Master policy type and deductible | A bare walls policy when you assumed walls-in coverage |
| Litigation disclosure | Suits the association is party to | Construction defect litigation, which can stop conventional financing outright |
Swipe the table sideways to see all columns.
Under the North Carolina Planned Community Act the seller must furnish a statement of unpaid assessments. Everything else on this list has to be asked for, which is why we ask on day one.
A title search finds what was recorded. Insurance pays for what it could not find. Everything in the second column is disclosed to you and then deliberately left out of the policy.
Insured by the owner's policy
Excepted, so read it before closing
| Policy | Who it protects | Amount | How long | Typical premium |
|---|---|---|---|---|
| Lender's policy | Required by your lender | The loan amount, falling as you pay down | Until the loan is paid off | About $2.20 per $1,000 of loan (sample) |
| Owner's policy | Optional, and the one that protects you | The full purchase price, fixed | As long as you or your heirs hold title | About $1.55 per $1,000 when issued simultaneously (sample) |
| Enhanced owner's policy | Optional upgrade on residential purchases | Purchase price, with automatic inflation increases | As long as you hold title | About 20% above the standard owner's rate (sample) |
Swipe the table sideways to see all columns.
General information about North Carolina practice, not legal advice. Your closing attorney advises you on your own title.
 2716 Anderson DrFive Points · listed $725,000 · 4 days$758,000
 114 Pine Hollow CtCary · listed $569,000 · 9 days$575,000
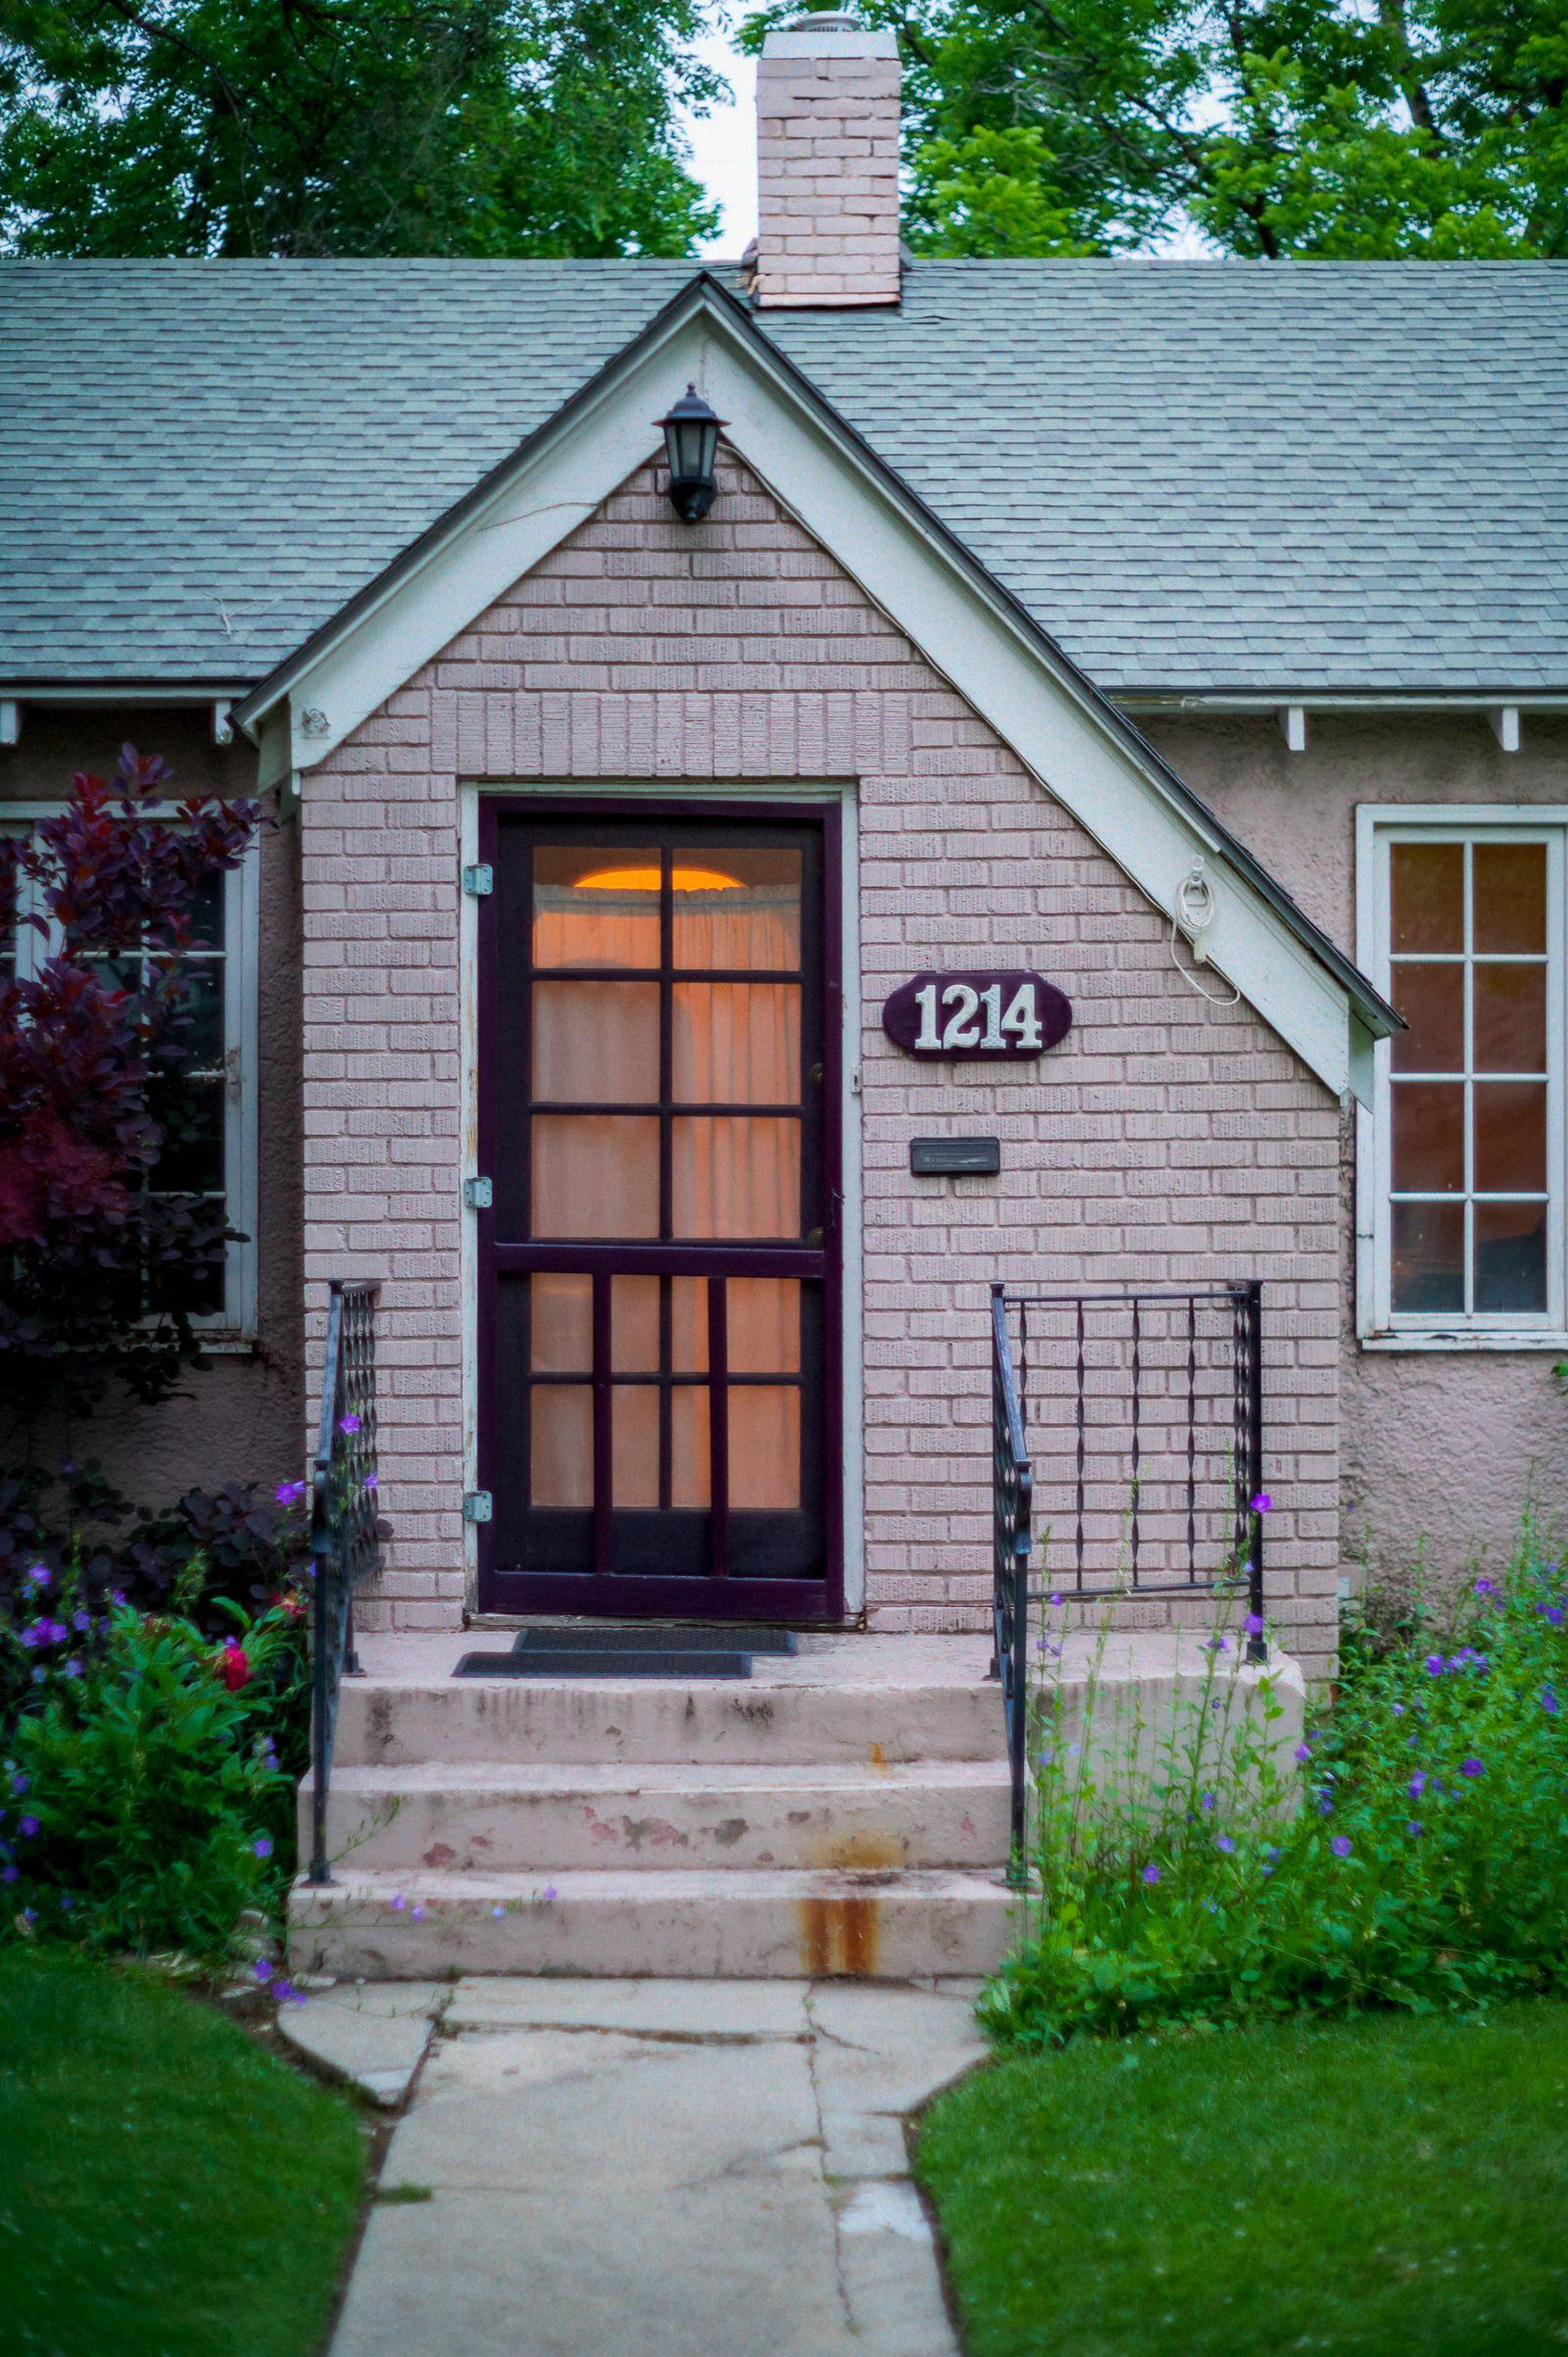 632 N Bloodworth StHistoric Oakwood · listed $689,000 · 12 days$702,500
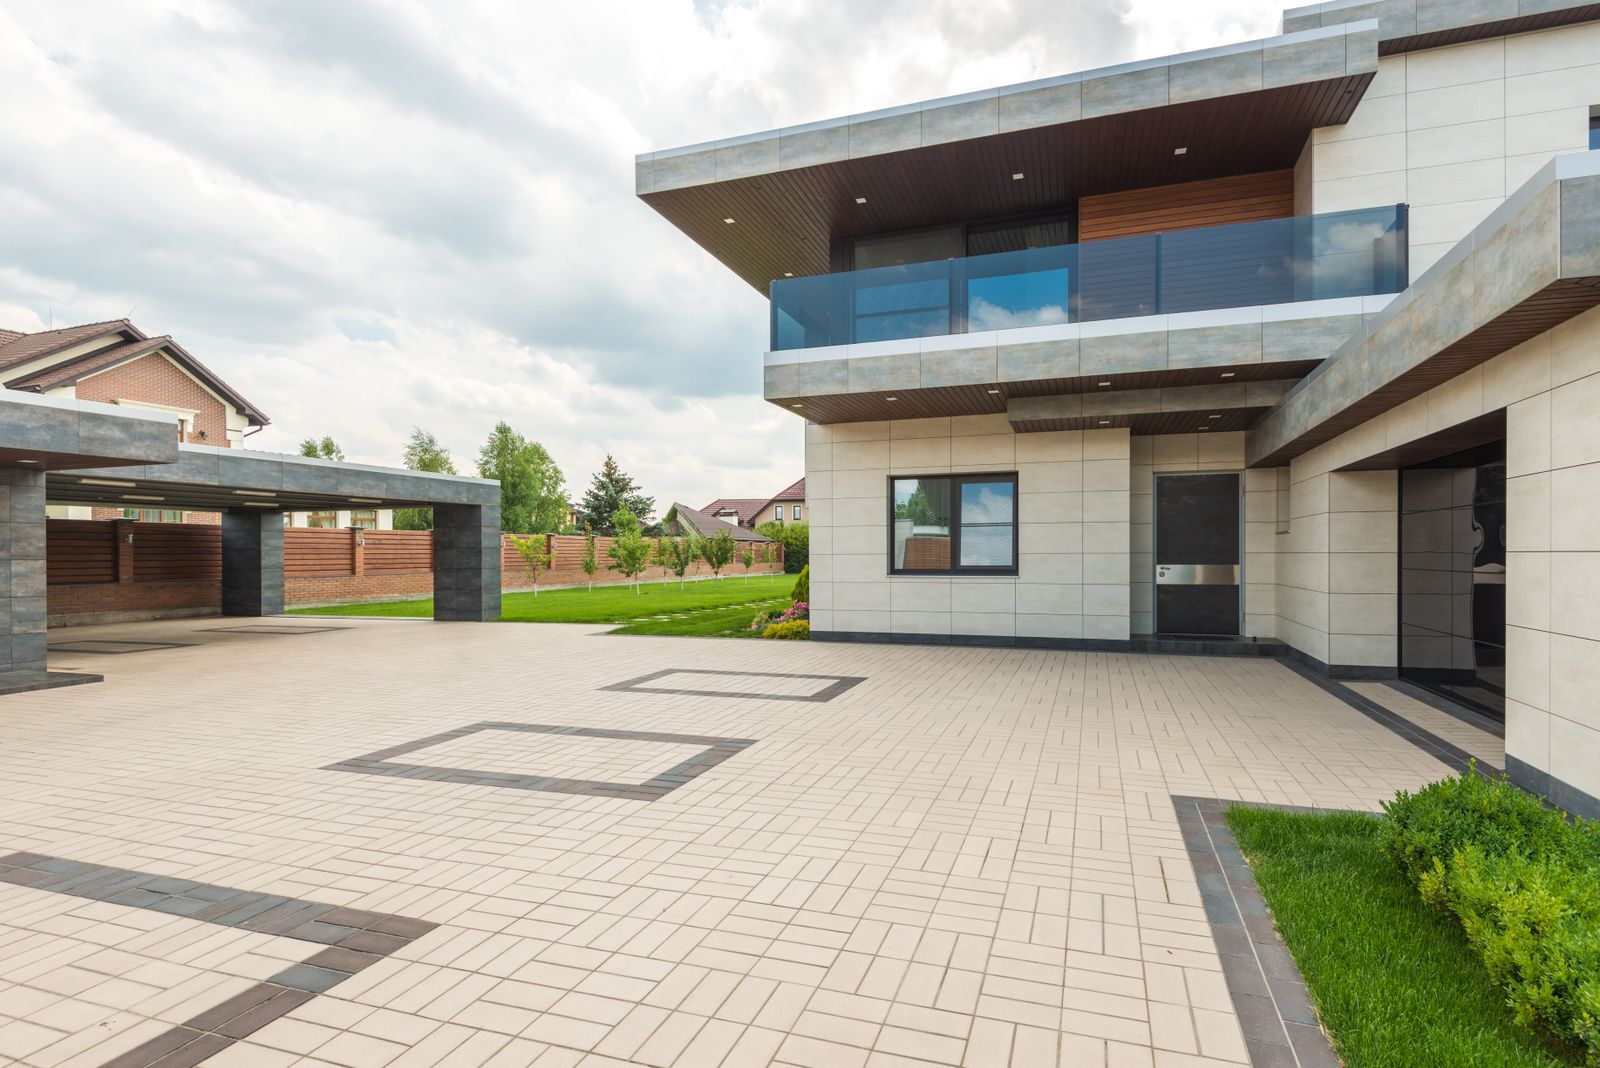 9810 Leesville TrailBrier Creek · listed $415,000 · 6 days$421,000
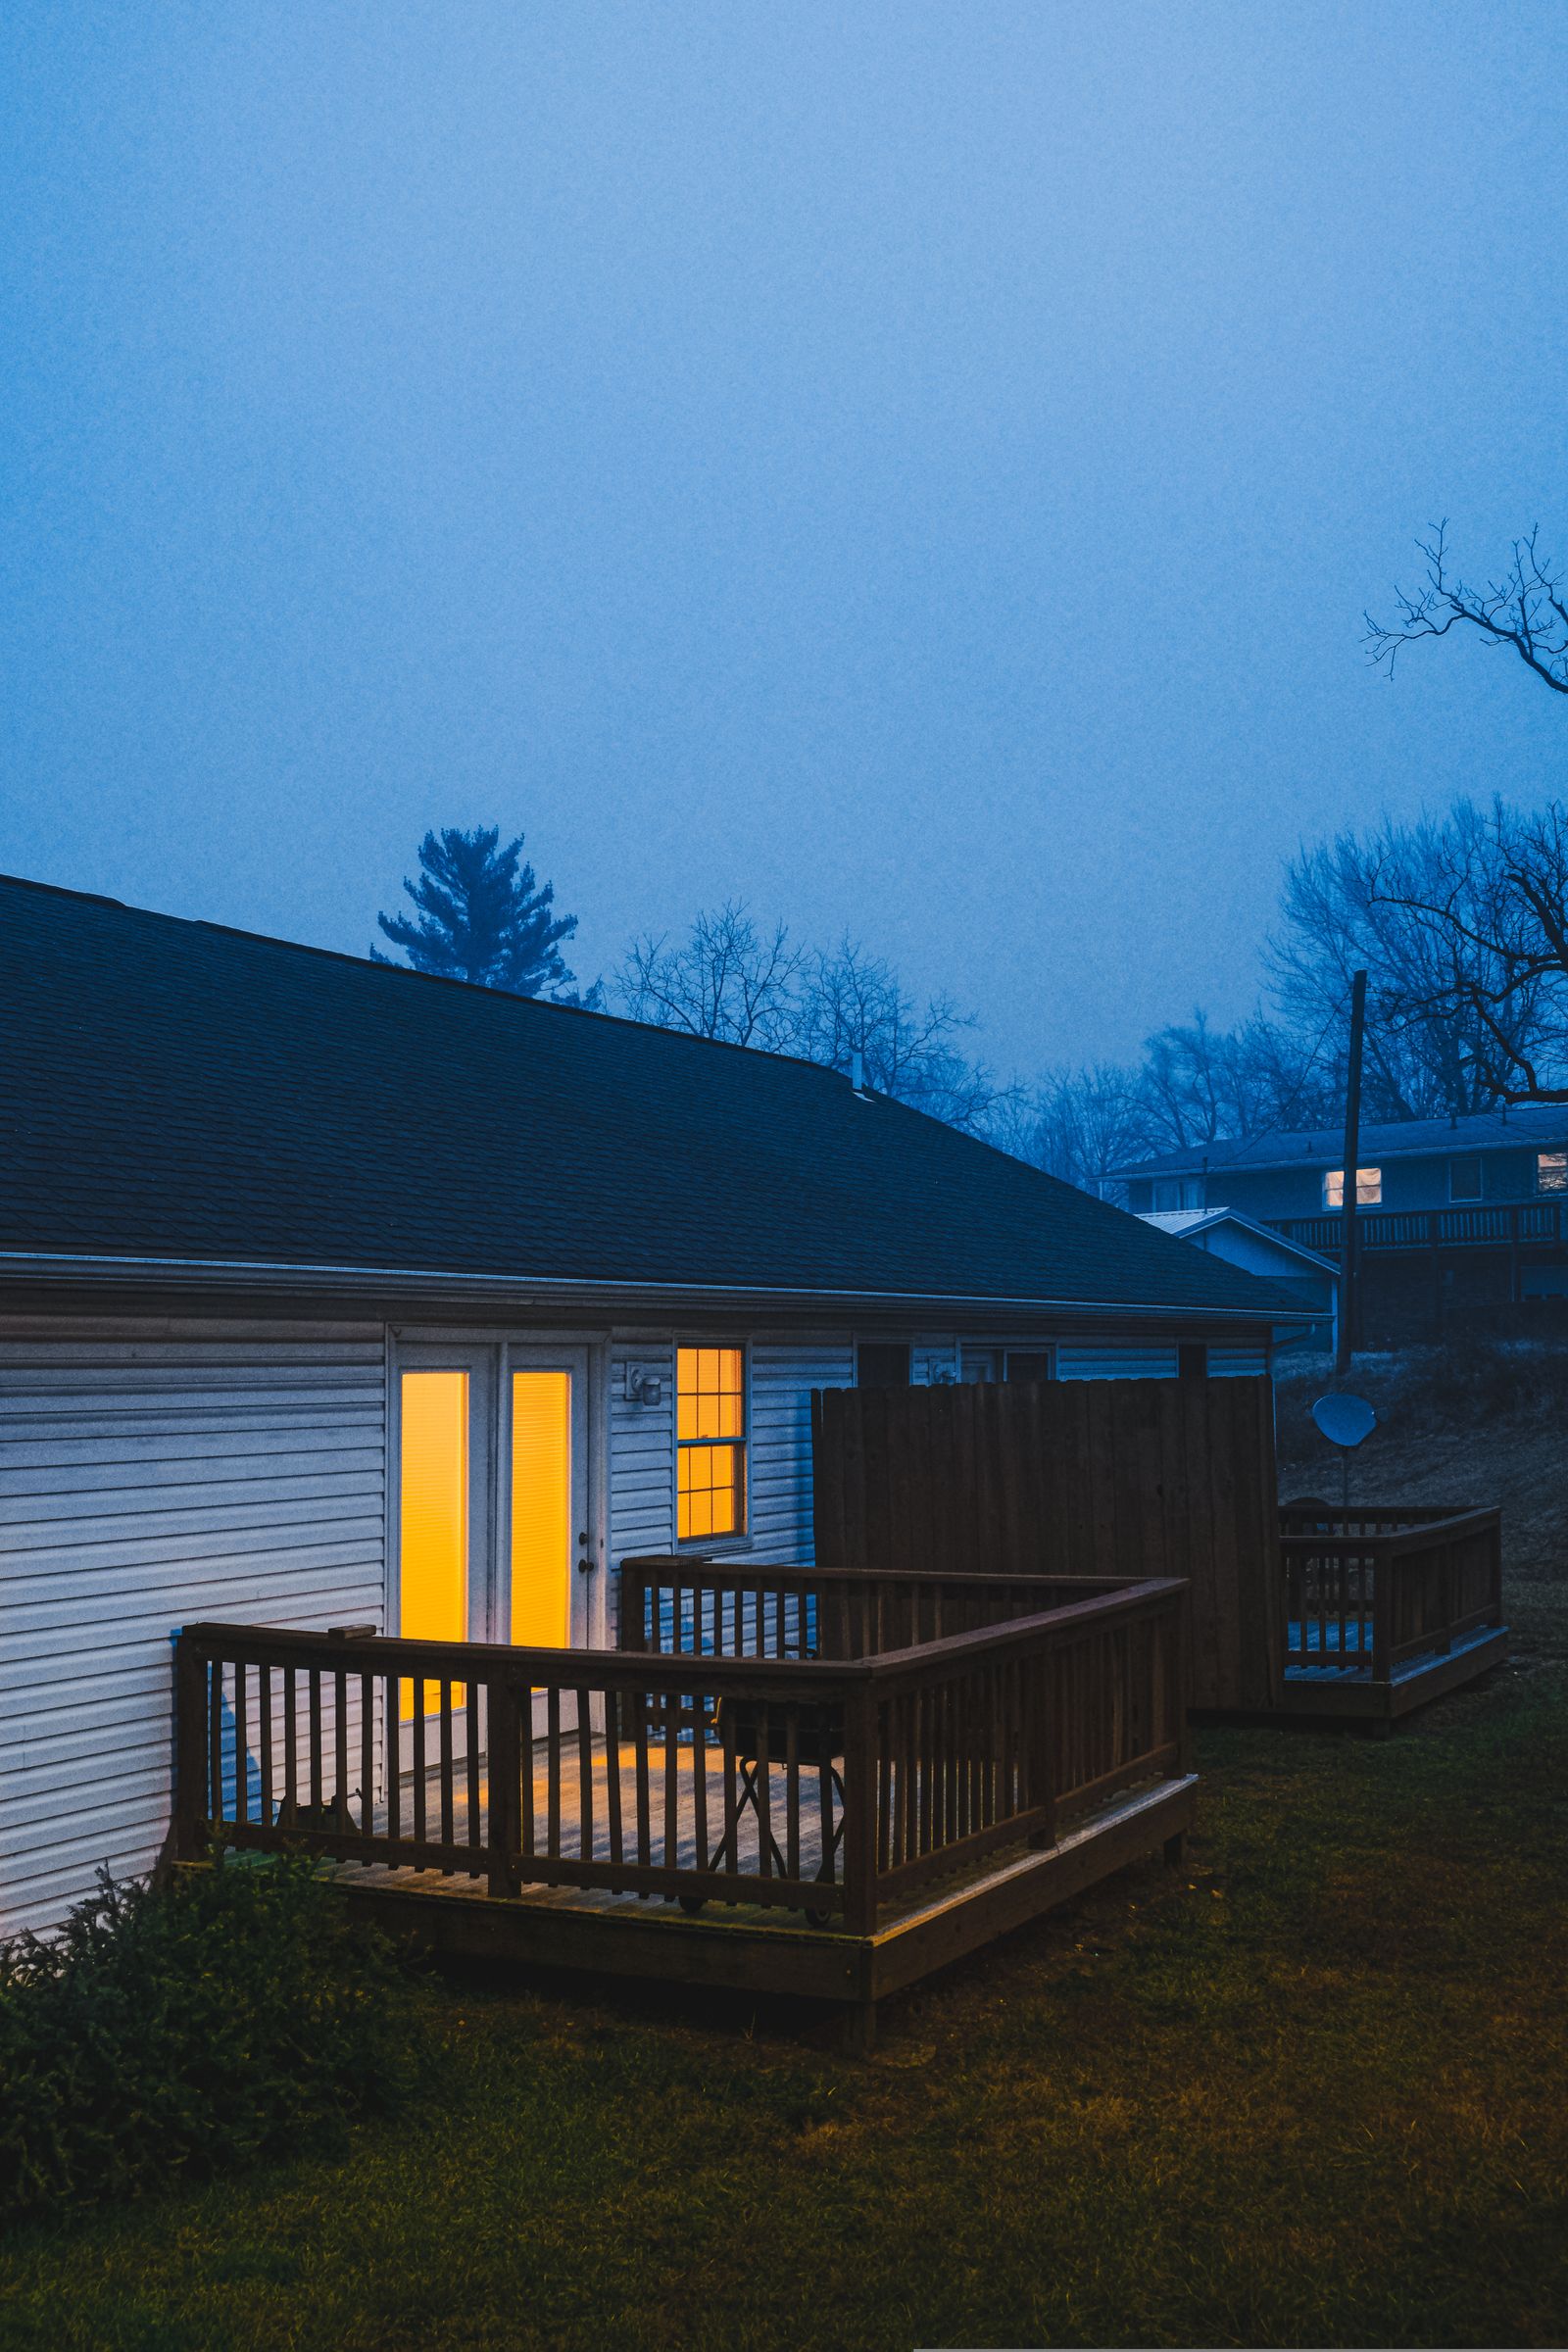 405 Wait AveWake Forest · listed $459,000 · 8 days$466,000
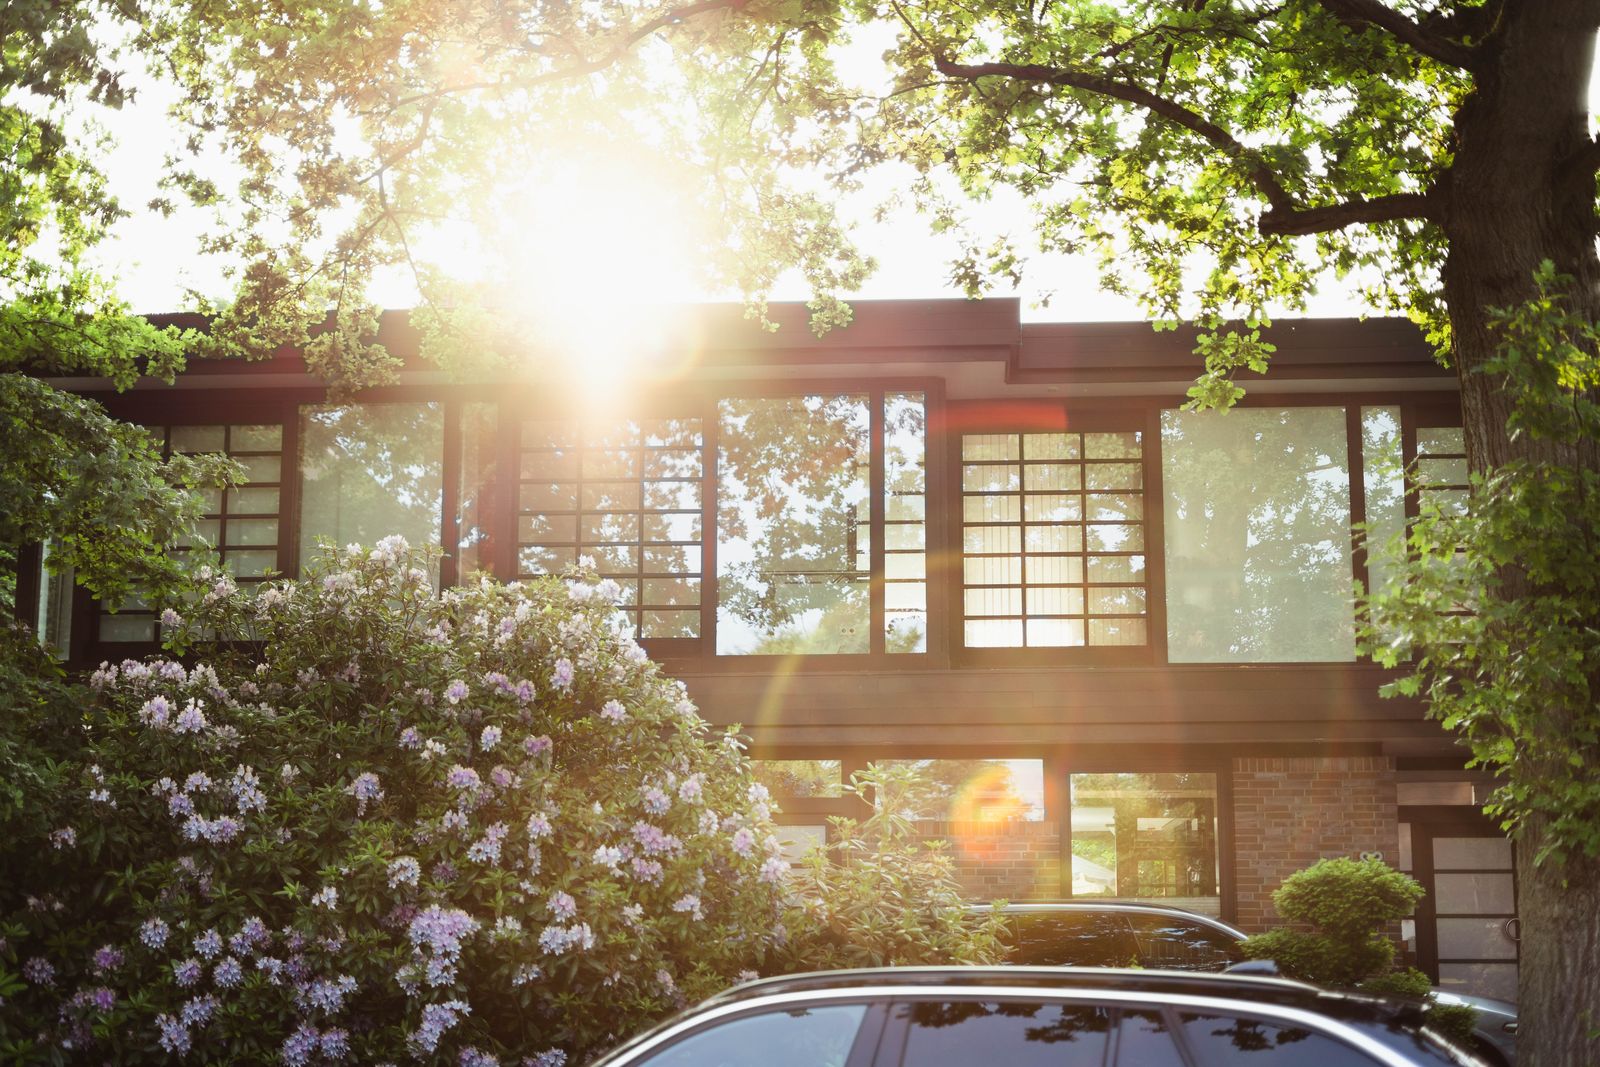 3021 Dogwood RdNorth Hills · listed $599,000 · 5 days$611,000
Sample figures for a demo website.
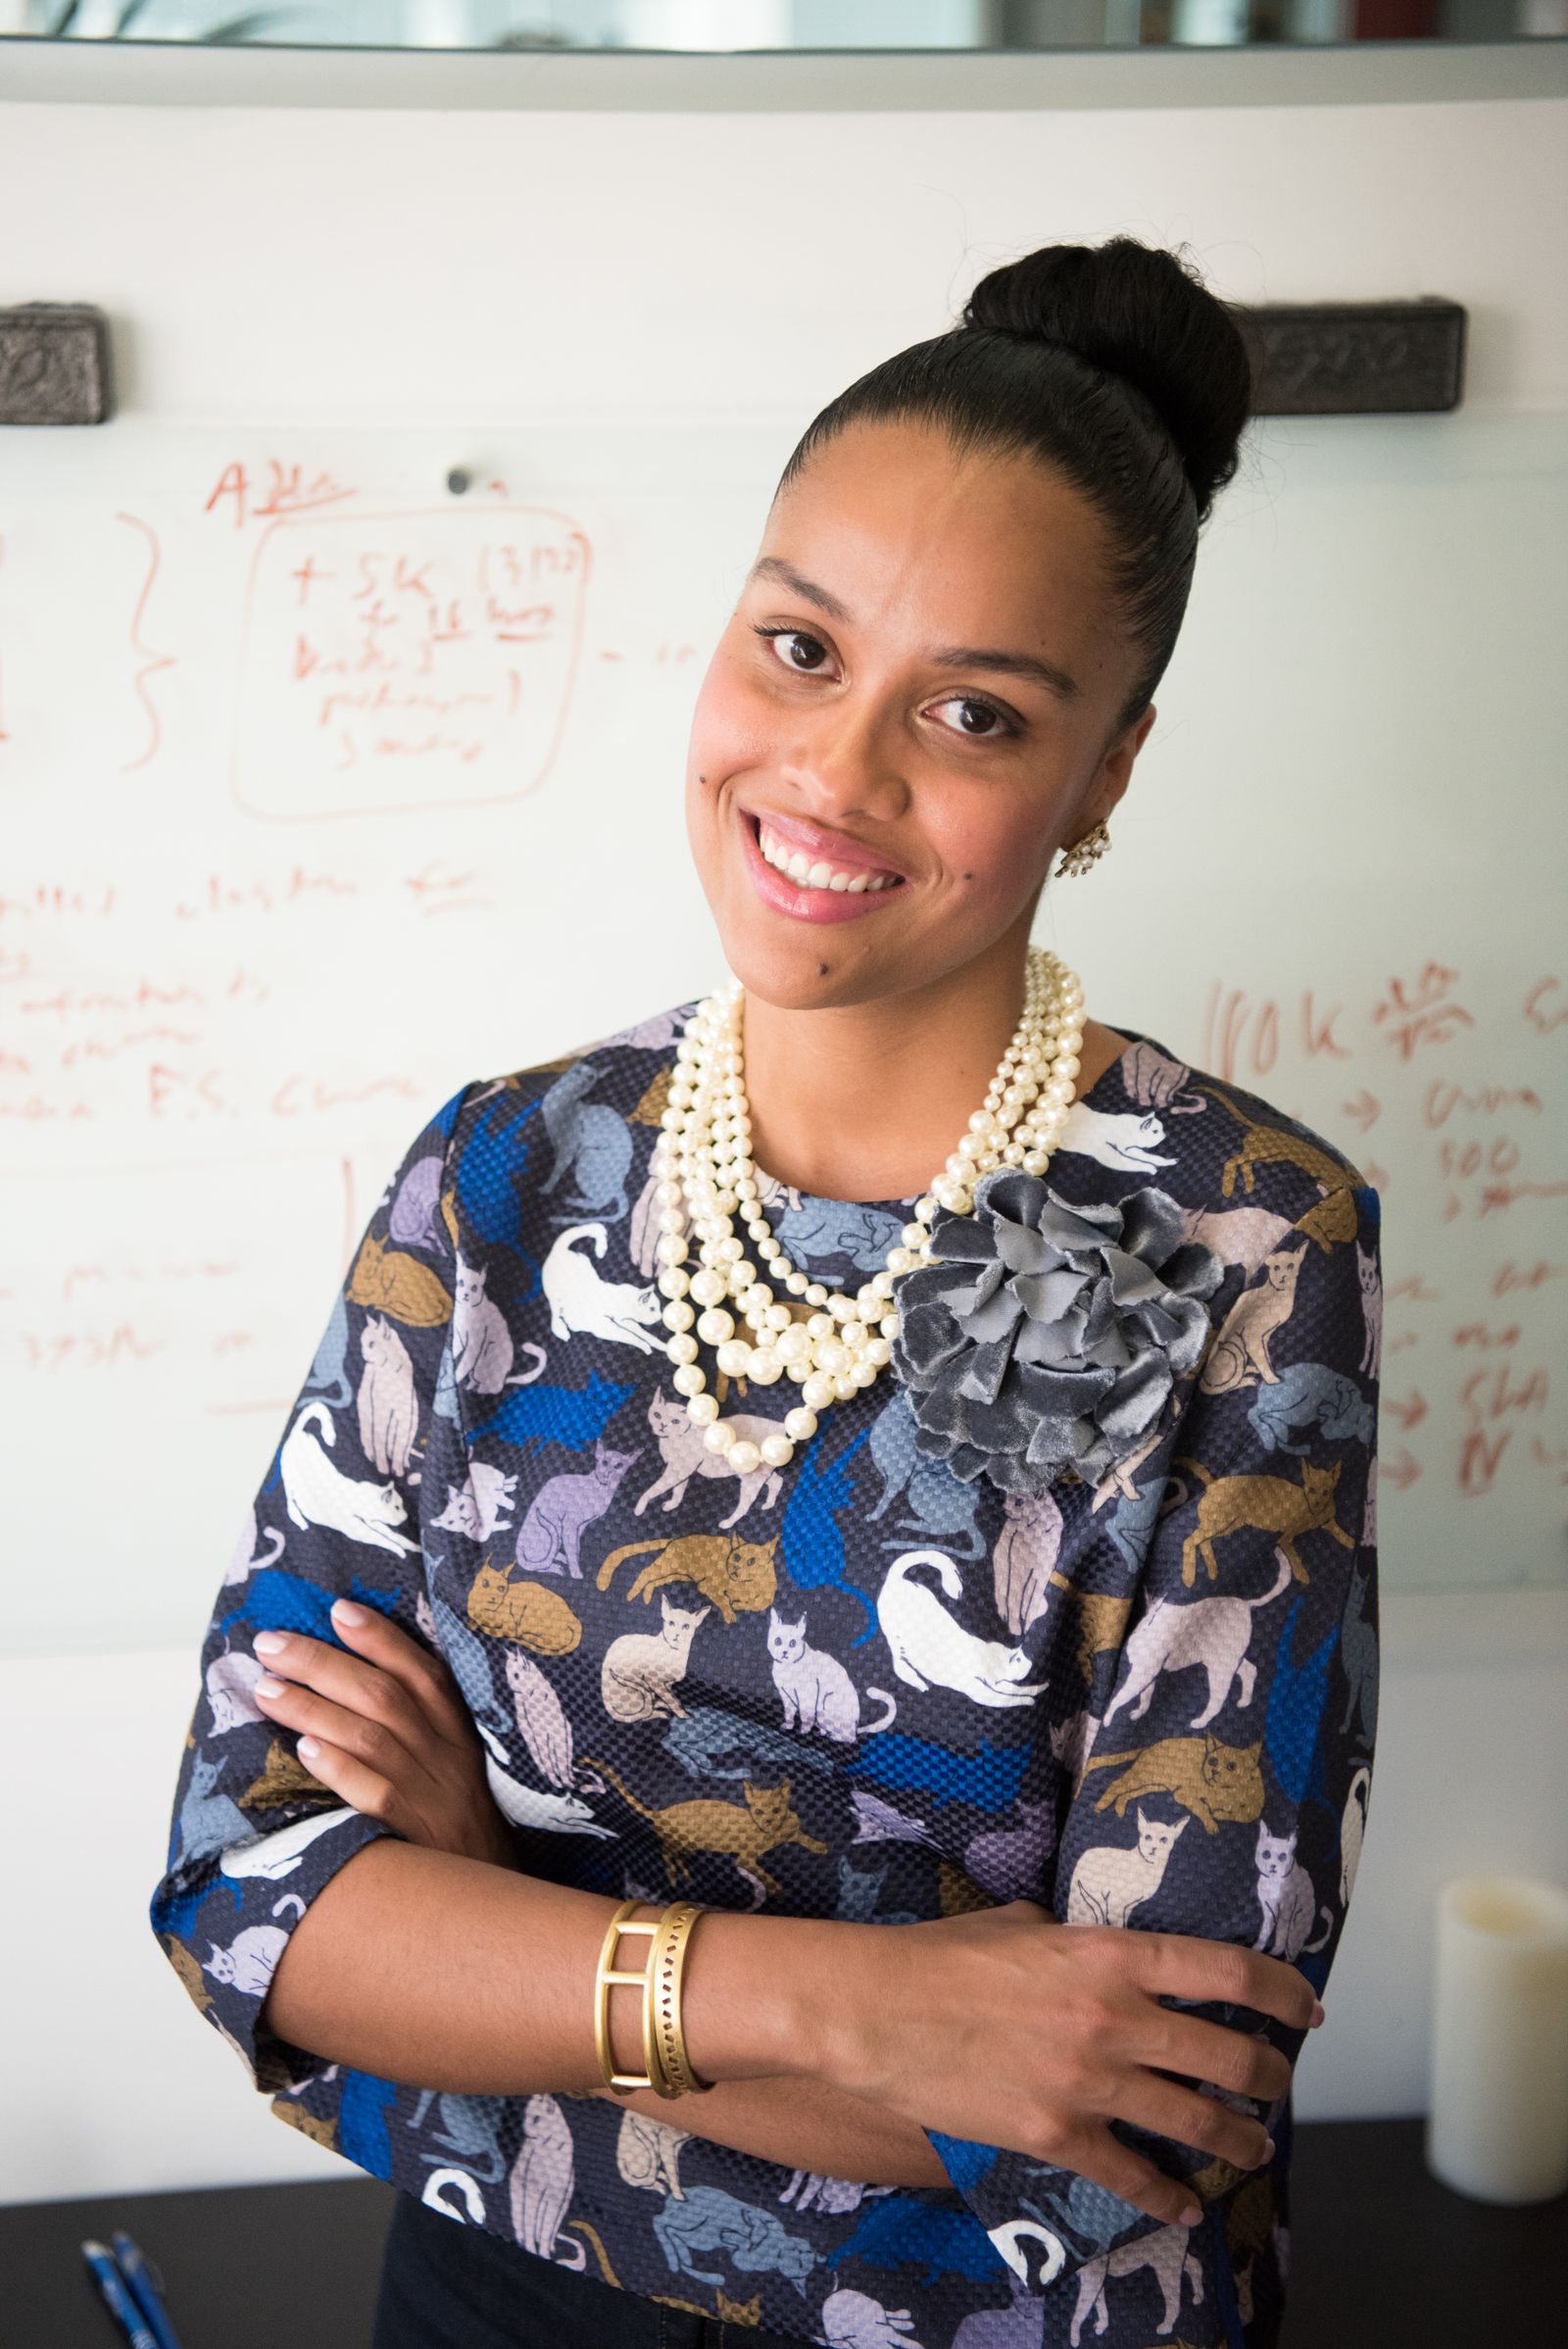
Founder and Broker-in-Charge
First-time buyers, North Hills
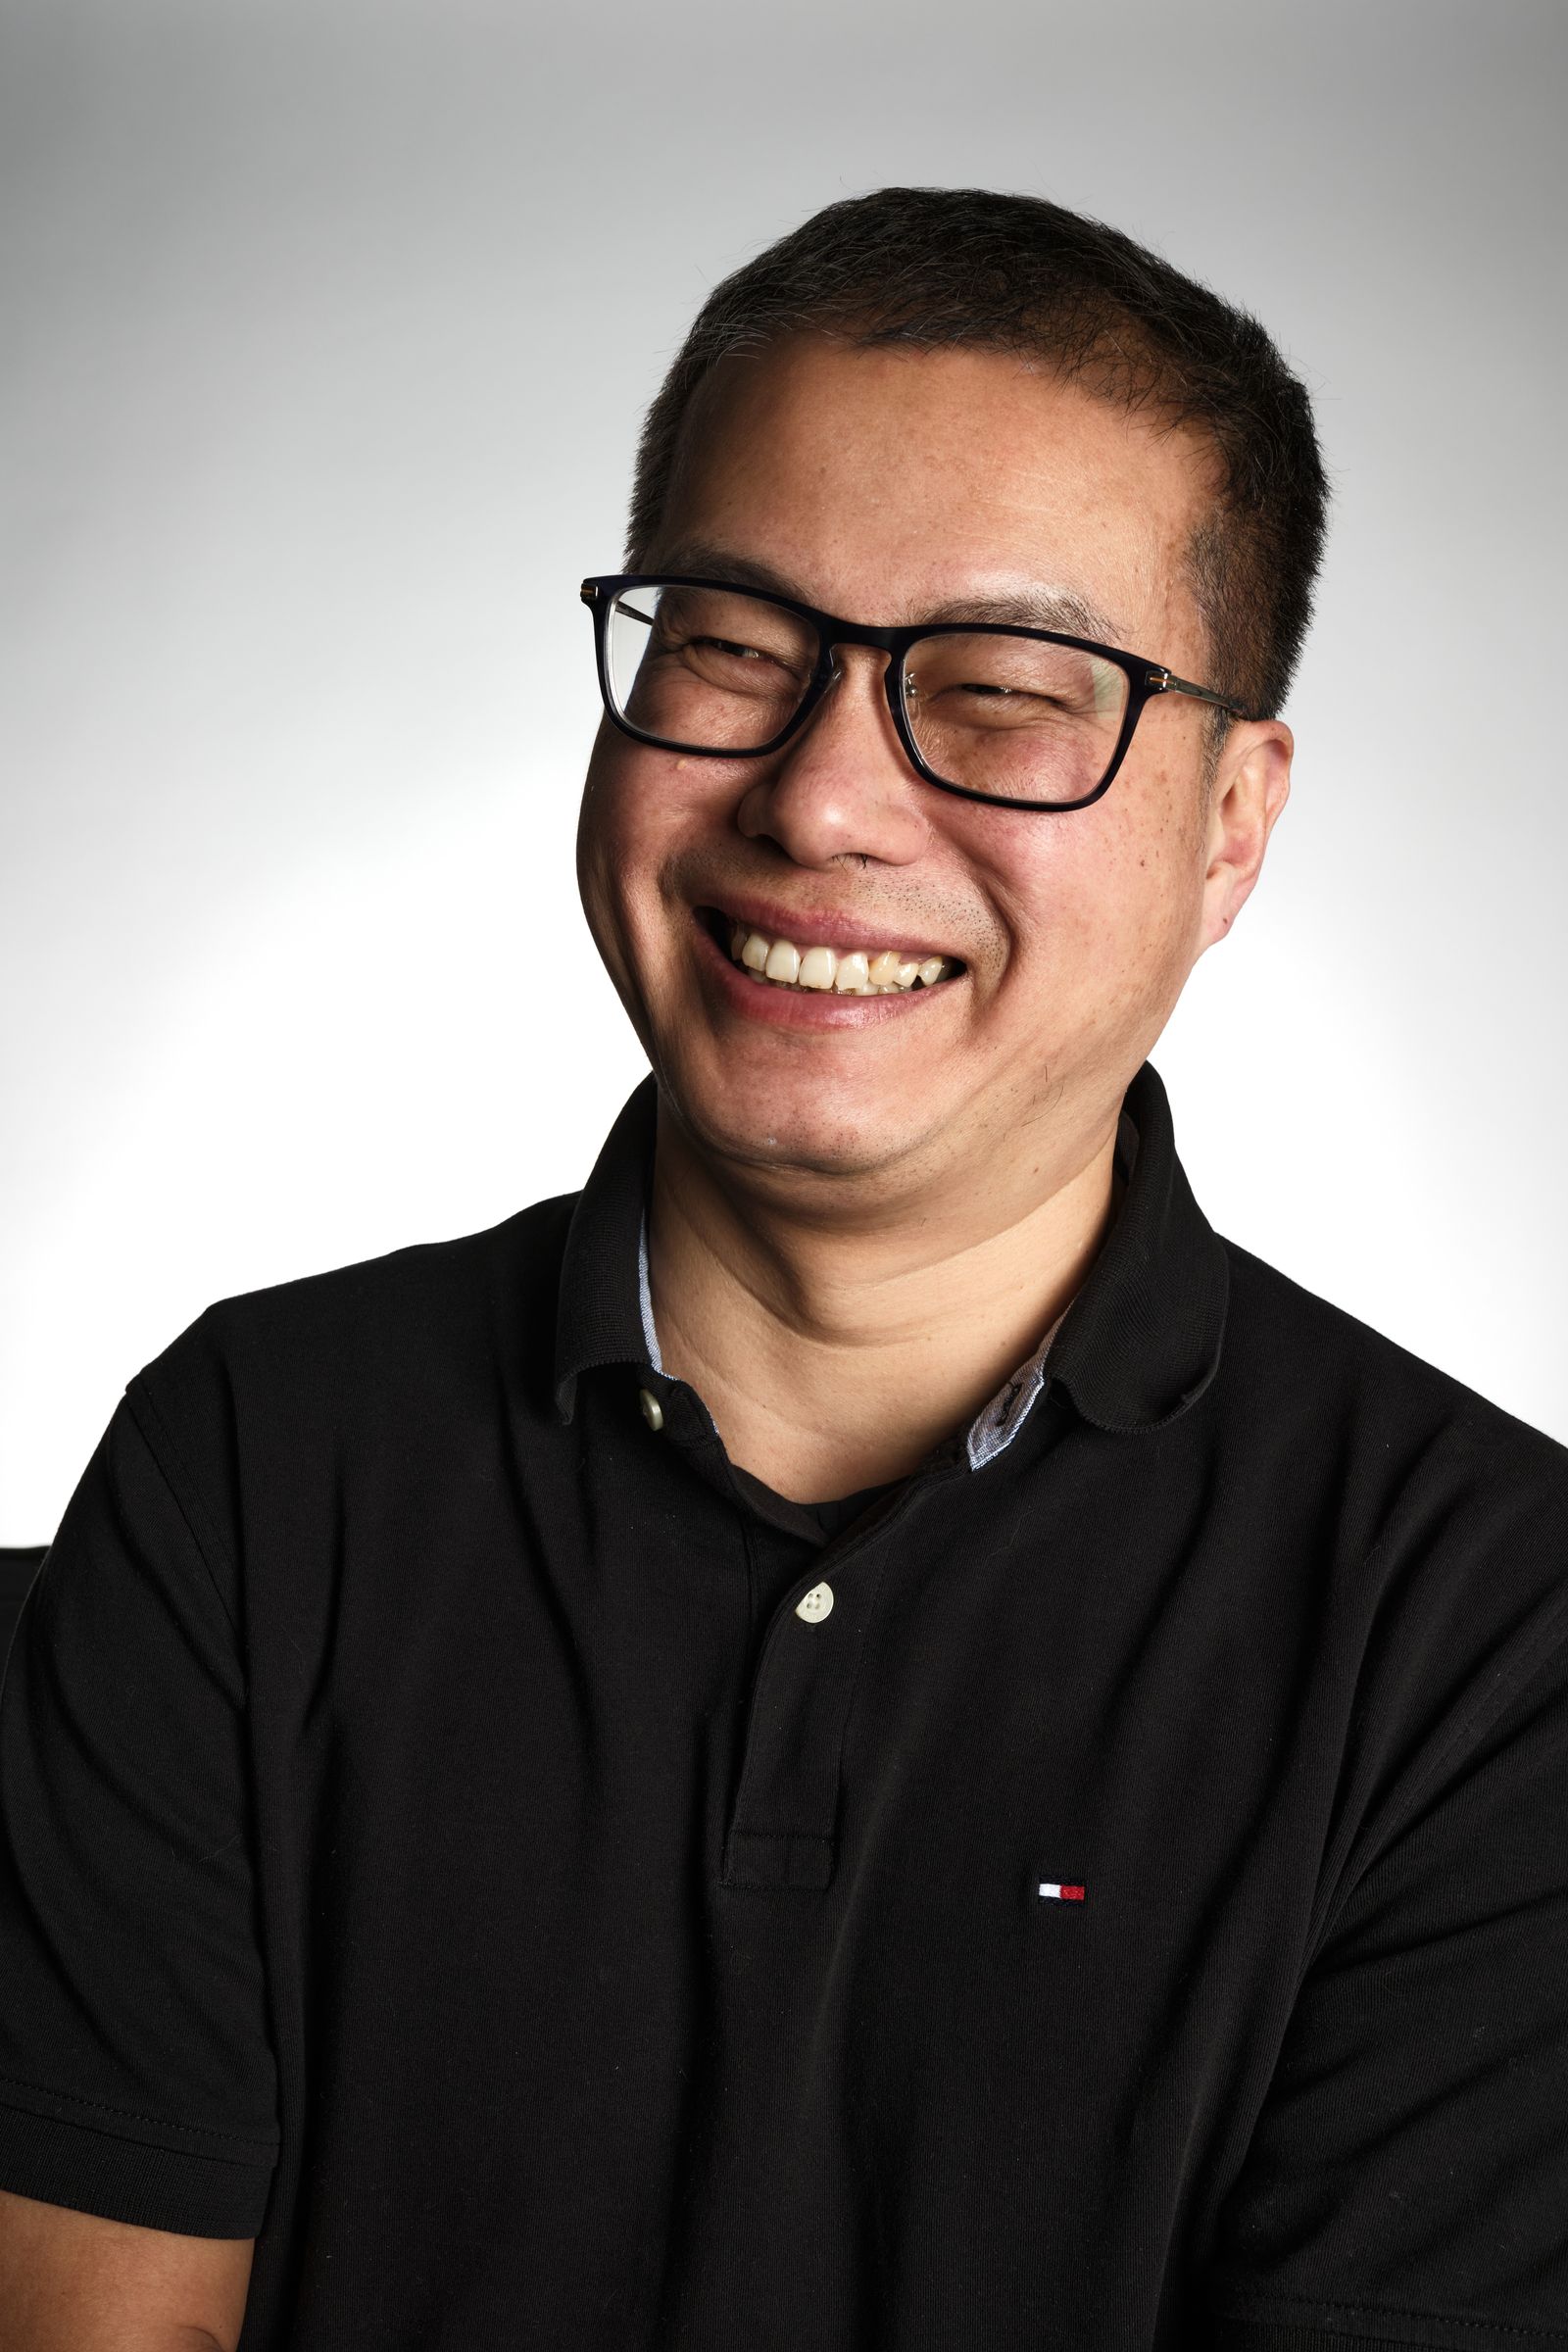
Listing Specialist
Home selling, Five Points
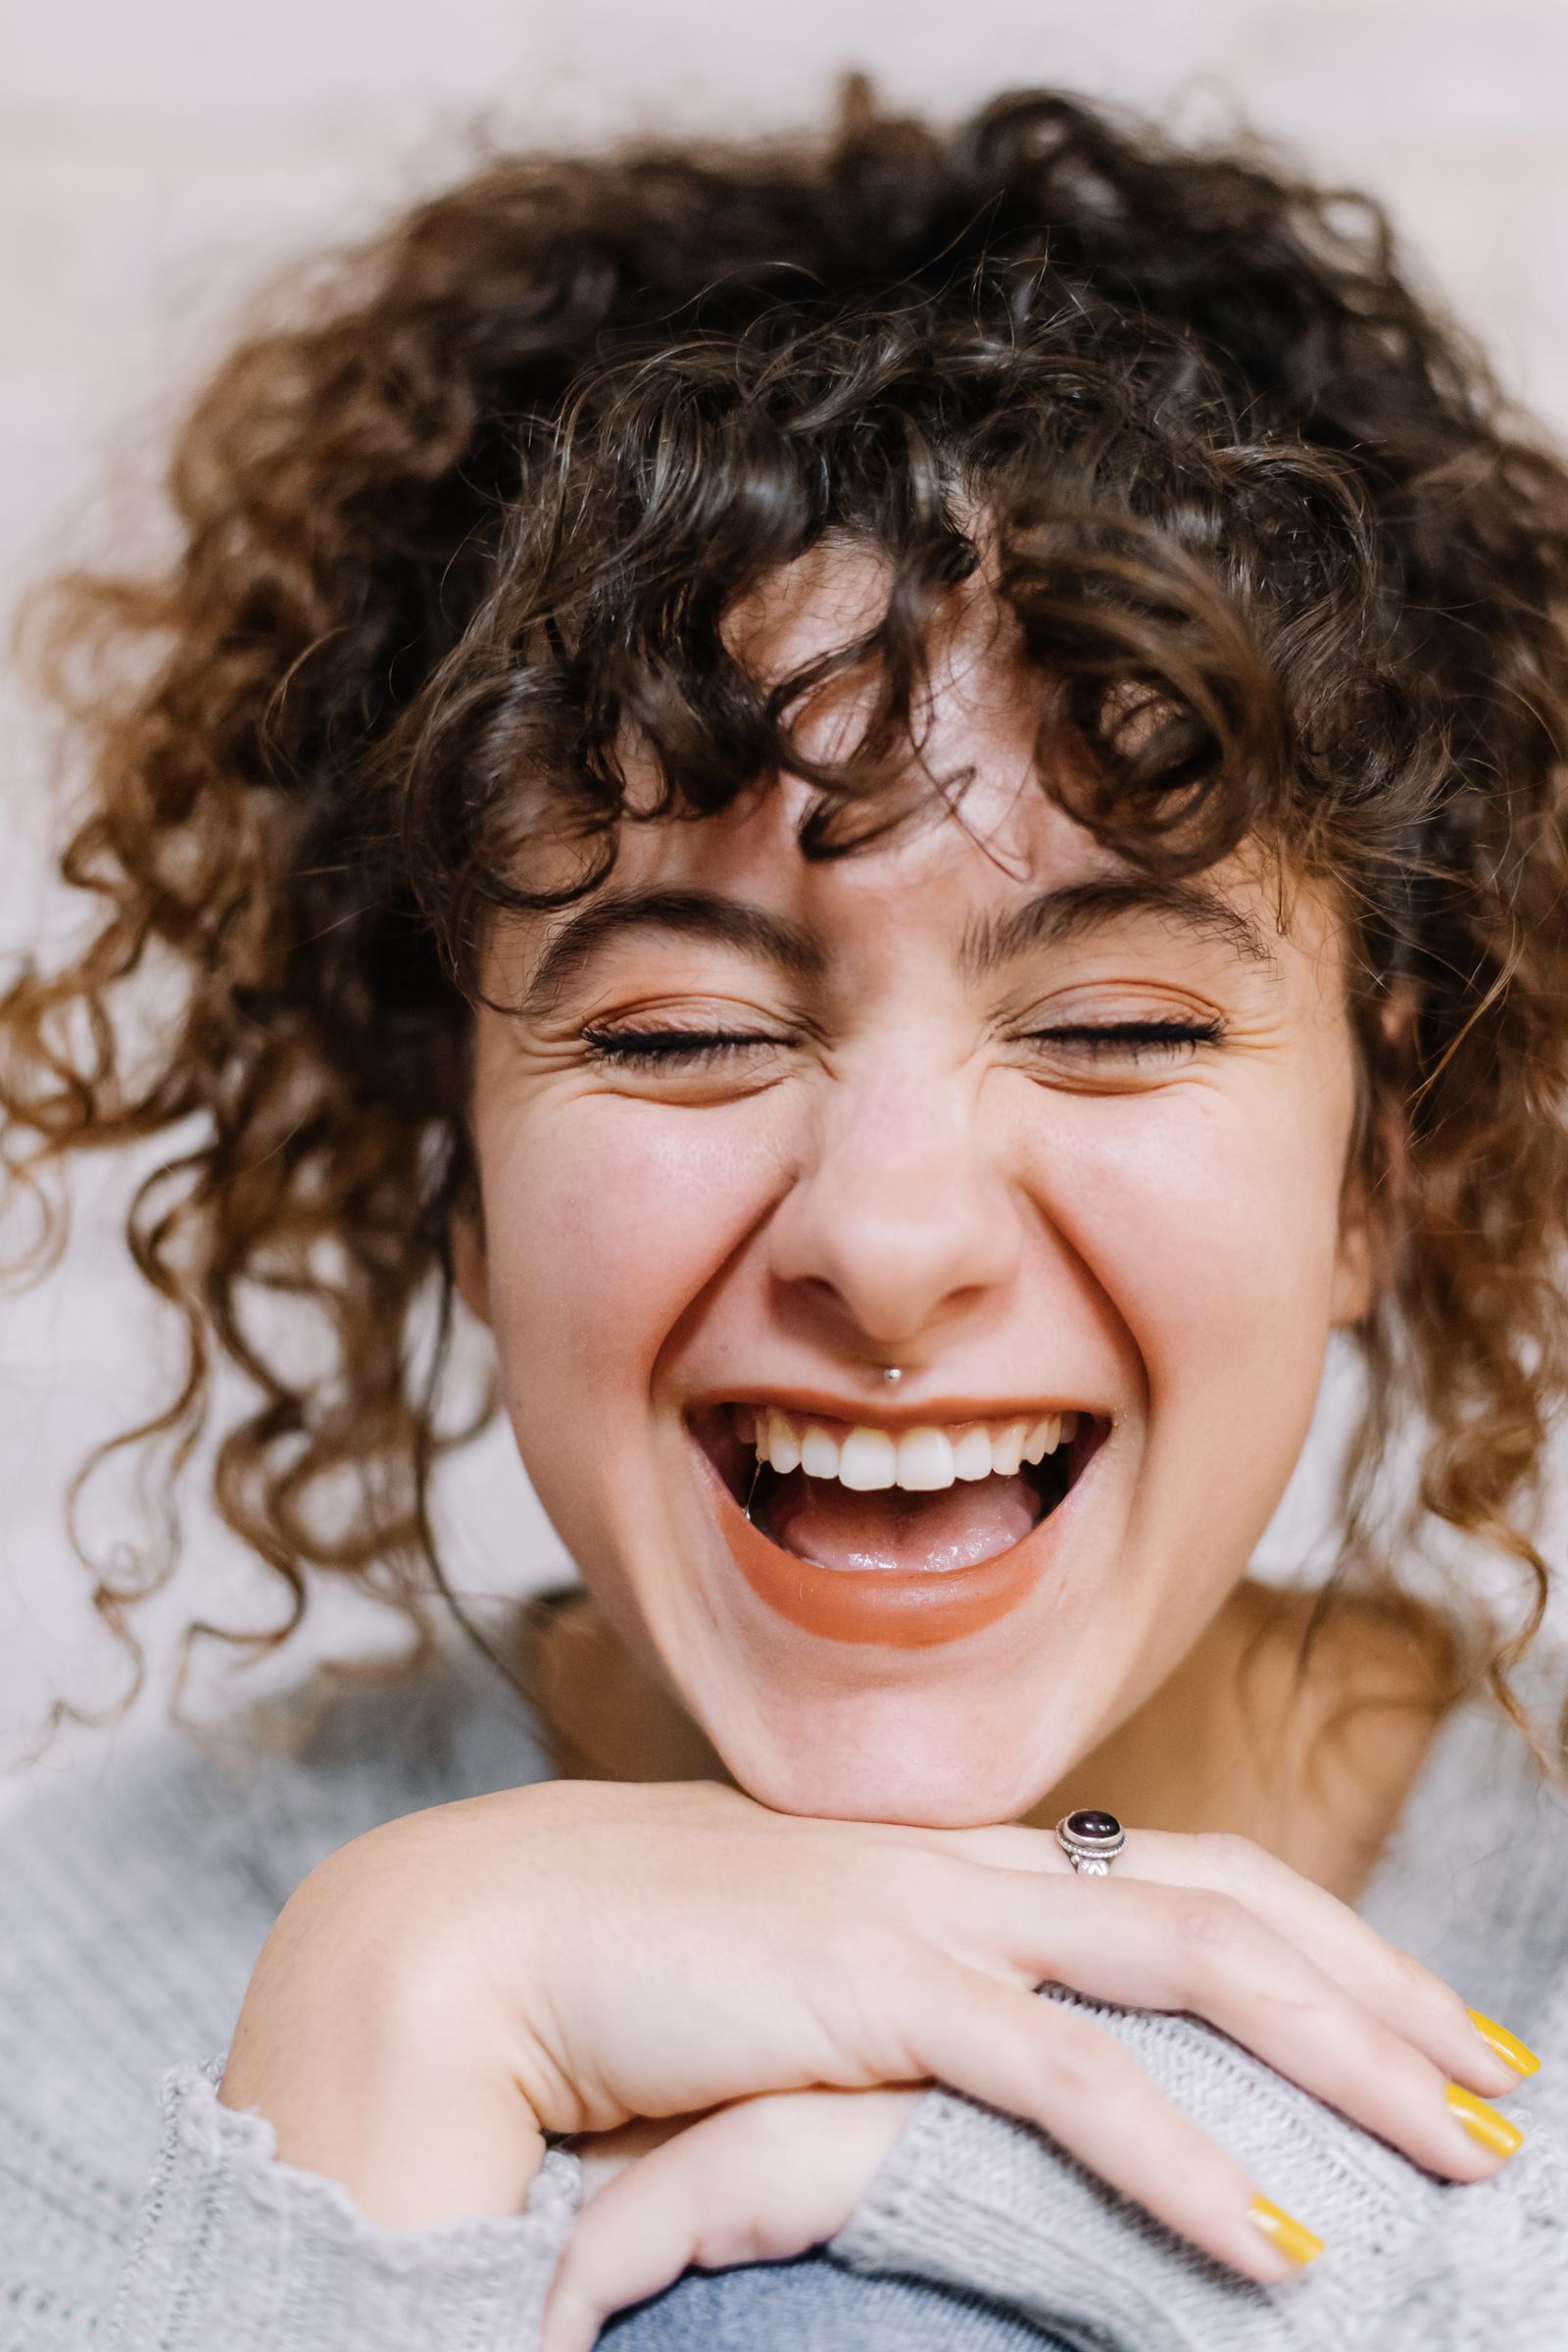
Buyer's Agent
Relocation, RTP commuters
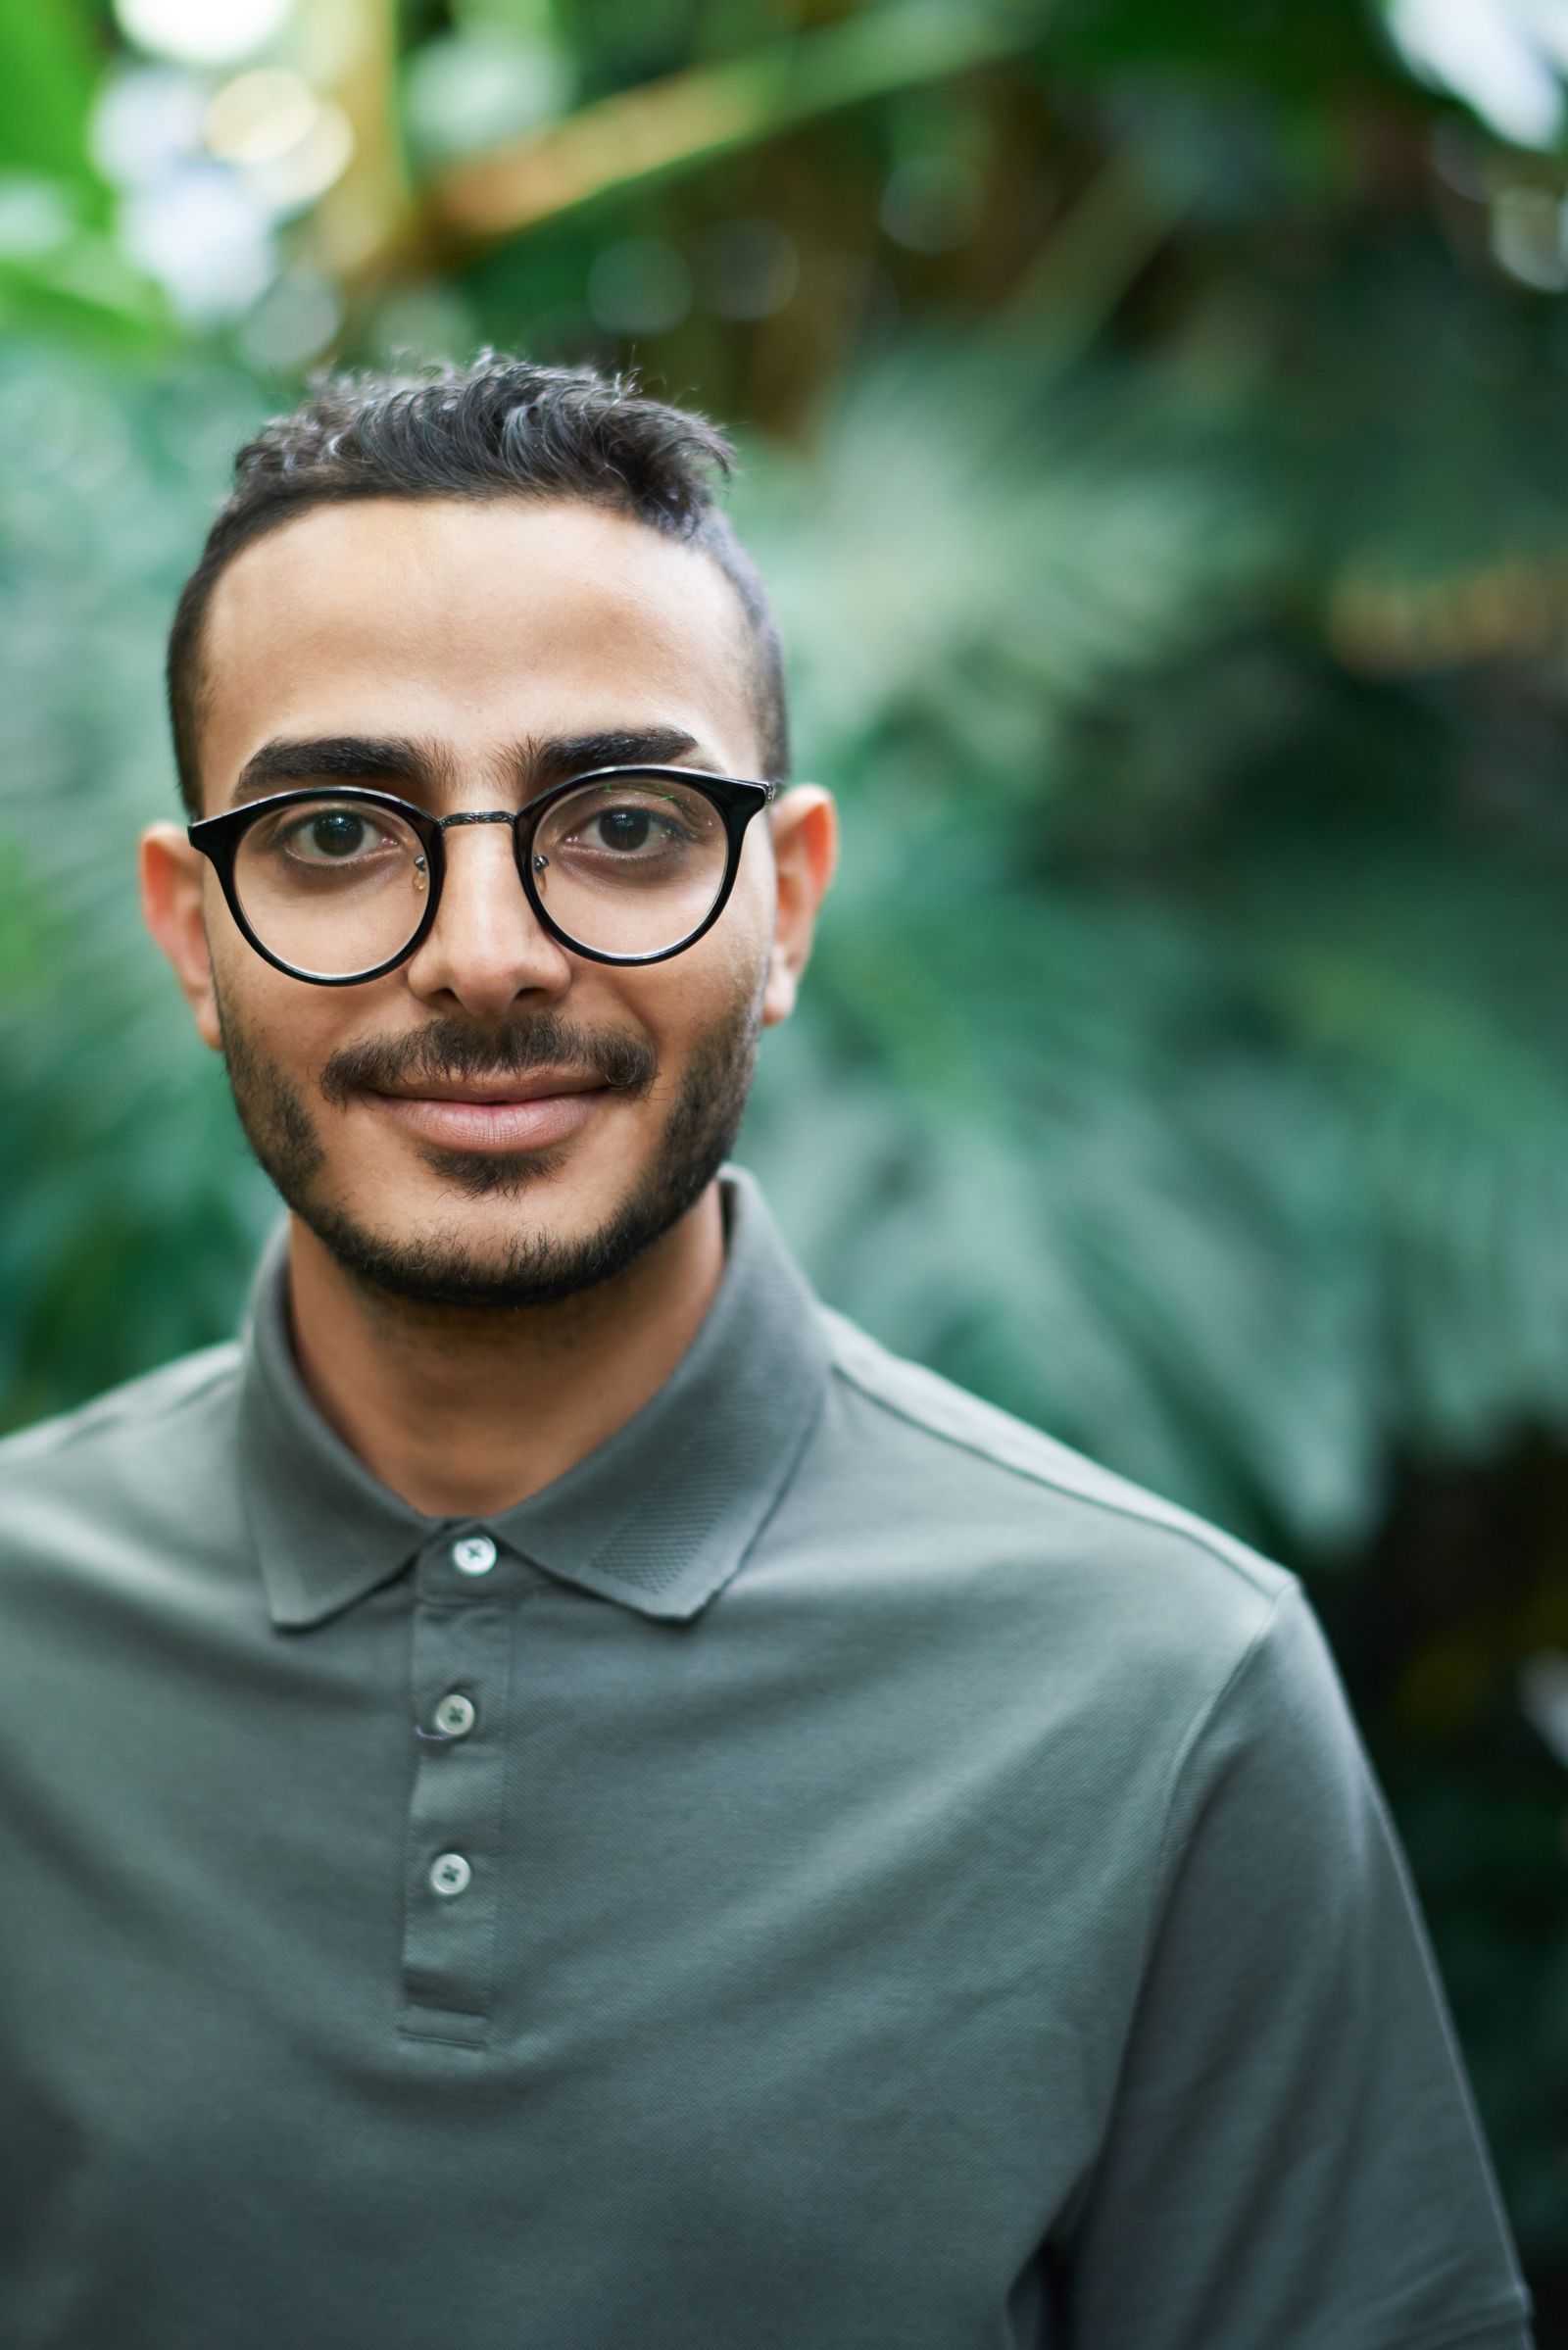
Buyer's Agent
VA and military buyers
First home, zero clue what due diligence meant. Tyler explained everything twice, never rushed us, and we closed on a house with a yard for our dog.
Marcus told us exactly which rooms to fix and which to leave alone. Seven showings the first day and we sold above asking in four days.
No hidden second level. If it exists here, it is in this list.
One email at the start of each month: what actually closed in your area, where list-to-sale ratios moved, and which contract terms buyers are winning with right now. Written by Renee, not by a marketing platform.
We value your privacy
We use cookies to run this site, remember your preferences and understand how it is used.Cookie policy